Financial Rights in a Long Island, New York Divorce
What financial rights and obligations should I evaluate in a New York divorce? Contact Us for a Free ConsultationCall 631-923-1910
Quick Answer
A Long Island, New York divorce requires more than dividing what you own today. You must determine which property is marital, which assets may remain separate, how debts will be paid, whether either spouse may owe spousal maintenance or child support, what will happen to the marital home, and how taxes, insurance and retirement benefits could affect the final result.
The analysis should also look forward. What will each household cost after separation? Can either spouse afford to keep the house? Will a mortgage need to be refinanced? Could the sale or transfer of an asset create a tax obligation? Does a business generate income or value that is not obvious from a personal tax return?
New York law provides a framework, but it does not guarantee either spouse a standard percentage or predetermined financial package. Your rights and obligations depend on the property, income, children, history and financial circumstances of your marriage.
“What Am I Entitled To?” Is Usually the Wrong First Question
Clients understandably want to know what they will receive. They may have heard that New York divides everything equally, that the parent with primary custody always keeps the house or that the higher-earning spouse must support the other indefinitely.
Those assumptions are unreliable or outright incorrect.
A useful financial analysis starts with different questions. What property exists? When and how was it acquired? What is it worth? Is there debt attached to it? Has either spouse made a separate-property claim? What income is available? What will the children need? Which obligations will continue after the marriage ends?
Only after those facts are developed can an attorney provide meaningful advice about a possible settlement or court outcome.
Divorce also involves obligations. You may have a claim to part of a retirement account while remaining responsible for a share of marital debt. You may keep the house but need to refinance the mortgage and compensate your spouse for an ownership interest. You may receive spousal maintenance while contributing toward childcare, healthcare or other expenses.
The financial result must be considered as a whole. Focusing on one asset or payment in isolation can produce an agreement that looks favorable but does not work in practice.
Why a Complete Financial Review Matters
Divorce restructures one household into two. The same income and property must now support separate homes, separate living expenses and, when children are involved, continuing responsibilities across both households.
Your divorce settlement will likely affect you for decades.
It could determine when the marital home will be sold, how retirement benefits will be divided, whether maintenance will be paid, who will be responsible for particular debts and how future expenses for the children will be shared. Some terms can later be modified under the right circumstances. Others, particularly provisions dividing property, are generally intended to be final.
Before negotiating, you need a reliable picture of the marital finances. That picture includes more than a list of bank balances. Income, liquidity, taxes, debt, insurance, future earning ability and the cost of maintaining an asset can matter just as much as its stated value.
A house worth $900,000 is not the same as $900,000 in cash. The house may carry a mortgage, taxes, insurance and repair costs. Selling it may involve commissions and other expenses. Keeping it may require refinancing. Its value on paper does not tell you whether retaining it is affordable.
That is why financial decisions should be tested, not simply totaled.
The Financial Issues at a Glance
| Issue | Questions to evaluate |
| Marital property | What was acquired during the marriage, and what is it worth? |
| Separate property | Can a spouse document ownership before marriage, an inheritance, a gift or another separate source? |
| Marital home | Will it be sold, transferred or retained temporarily, and who can afford it? |
| Retirement benefits | What portion is marital, and what documents are needed to divide it? |
| Business interests | What is the business worth, what income does it produce and how will it be treated? |
| Debt | Which debts are marital, who will pay them and can joint liability be eliminated? |
| Spousal maintenance | Is maintenance appropriate, and if so, in what amount and for how long? |
| Child support | What income will be used, and how will additional child-related expenses be allocated? |
| Taxes | Will transfers, sales, support provisions or filing decisions create tax consequences? |
| Insurance | How will health, life, property and other coverage continue after divorce? |
| Attorney and expert fees | Does either spouse have a claim or potential obligation for litigation expenses? |
| Post-divorce cash flow | Can each spouse meet expenses after the settlement takes effect? |
Marital Property and Separate Property
New York follows the principle of equitable distribution (as opposed to “community property”). This means marital property is divided fairly after the court considers the relevant circumstances. It does not mean every asset is automatically divided in half.
Marital property generally includes assets acquired by either spouse during the marriage and before the execution of a separation agreement or the commencement of a matrimonial action, regardless of whose name appears on the account, deed or title. A paycheck deposited into an individually titled account may still be marital. So may retirement contributions made through one spouse’s employment.
Separate property can include assets owned before the marriage, an inheritance received by one spouse, certain gifts from someone other than the other spouse and compensation for some personal injuries. The classification is not always permanent or obvious.
A separate asset can become difficult to trace if it is mixed with marital funds. A premarital account may contain both separate and marital contributions. Inherited money may be deposited into a joint account and used to purchase jointly titled property. One spouse may own a house before marriage, while marital funds are later used to pay its mortgage or fund improvements.
Documentation matters. Bank statements, closing records, account histories and other evidence may be necessary to trace a separate-property claim.
Title alone does not settle the question. Neither does memory.
The Marital Home
For many families on Long Island, the marital home is both the largest asset and the most emotionally charged financial issue.
There are several possible outcomes for the marital home in a divorce. The property may be sold and the net proceeds divided. One spouse may buy out the other’s interest. A sale may be postponed for a period, perhaps to provide stability for the children. In some cases, the spouses may continue owning the property together temporarily.
Each approach creates practical questions.
If one spouse wants to keep the house, that person should examine whether the mortgage can be refinanced and whether the ongoing expenses are manageable on one household’s post-divorce income. Mortgage payments are only part of the calculation. Property taxes, insurance, utilities, maintenance and repairs must also be considered.
A buyout requires an agreed value or appraisal, a method for calculating equity and a deadline for payment. The agreement should state what happens if refinancing is denied or the payment is not made on time.
Joint ownership after divorce carries risk. Both spouses may remain exposed to mortgage liability even if only one continues living in the home. A missed payment can damage both parties’ credit. The settlement needs clear deadlines, responsibilities and remedies.
Keeping the house may feel like winning. If the cost prevents you from meeting other needs or saving for retirement, it may not be the best financial result.
Bank Accounts, Investments and Deferred Compensation
Checking and savings accounts are usually easier to identify than other assets, but even ordinary accounts can raise questions about ownership, deposits and withdrawals.
Investment accounts add market risk and tax considerations. Two portfolios with the same stated value may not have the same after-tax value. One may contain appreciated securities that will generate capital gains when sold. Another may hold cash or investments with a higher cost basis.
Executive compensation can be more complicated. Restricted stock units, stock options, bonuses, commissions and other deferred compensation may have been earned during the marriage but paid or vested later. Employment agreements and plan documents may be needed to determine whether some portion should be treated as marital.
A settlement should specify the valuation date, division method and responsibility for taxes and transaction costs. “We will divide the account equally” may not be enough.
Retirement Accounts and Pensions
Retirement assets are easy to undervalue because they do not affect today’s checking-account balance. They may nevertheless represent a substantial part of the marital estate.
The marital portion of a 401(k), 403(b), pension or other retirement benefit may be subject to equitable distribution. Contributions made before the marriage may remain separate, while contributions and growth during the marriage may be marital.
Different plans require different division procedures. Some employer-sponsored plans require a Qualified Domestic Relations Order, commonly called a QDRO. Government and public-sector retirement systems may use other forms of domestic-relations orders or plan-specific documents.
The settlement should address more than a percentage. Valuation dates, investment gains and losses, outstanding loans, survivor benefits, administrative fees and tax treatment may all matter.
A pension presents another choice: divide the future benefit, offset its value against another asset or negotiate a different arrangement. Each option carries risk. An offset may depend on assumptions about life expectancy, retirement age, interest rates and the reliability of the valuation.
Retirement provisions should be coordinated with the documents that will actually implement them. Waiting years to prepare the necessary order can create serious problems.
Businesses and Professional Practices
A business interest acquired or developed during the marriage may be marital property even when only one spouse works there or holds legal title.
Business valuation is not the same as reading the balance shown on a company bank statement. The analysis may consider assets, liabilities, earnings, cash flow, market conditions, ownership restrictions and goodwill. Compensation and personal expenses paid through the business may also affect income calculations for maintenance or child support.
The goal is not necessarily to divide the business itself. Often, the operating spouse retains ownership while the other spouse receives an offsetting distribution, installment payments or another form of compensation.
Care is needed to avoid counting the same economic benefit twice. A business’s income may affect its value and also be considered for support. The relationship between those calculations should be evaluated rather than assumed.
Buy-sell agreements, shareholder restrictions and prior valuations may provide information, but they do not always control the value used in divorce.
Marital Debt and Joint Liability
Assets receive most of the attention, but debt can be just as important.
Mortgages, credit cards, personal loans, tax liabilities and other obligations may need to be classified and allocated. A debt incurred during the marriage is not automatically marital in every circumstance, but many debts used for household or family purposes will be part of the financial analysis.
The divorce agreement can assign responsibility between the spouses. It cannot necessarily prevent a creditor from pursuing anyone whose name remains on the account.
Suppose the settlement requires your spouse to pay a joint credit card. If your name remains on the account and payments stop, the creditor may still pursue you. Your credit may also suffer.
The better solution may involve paying and closing the account, refinancing the debt or establishing another mechanism that removes joint exposure. When that is not immediately possible, the agreement should provide safeguards and remedies.
Review recent statements carefully. Changes in spending, unusual withdrawals, cash advances or new debt may require investigation.
Spousal Maintenance
Spousal maintenance, often called alimony outside New York, is not automatically awarded in every divorce.
New York uses statutory calculations for temporary maintenance during a pending divorce and for post-divorce maintenance. Those calculations provide a starting point, subject to applicable income caps, statutory factors and possible deviations.
The amount is only one issue. Duration matters. So do termination events, payment method, security and the interaction between maintenance and the rest of the settlement.
A spouse may waive maintenance in exchange for a larger share of another asset. That may be reasonable, but only after comparing the value, tax treatment, liquidity and risk of each option. Giving up monthly support for an asset that cannot generate cash may leave the recipient unable to meet ordinary expenses.
The paying spouse should evaluate affordability using realistic post-divorce income and expenses. The receiving spouse should consider whether support will be enough, how long it will continue and what financial adjustments will be necessary when it ends.
Child Support and Children’s Expenses
New York calculates basic child support under the Child Support Standards Act. The calculation begins with parental income as defined by law, applies specified deductions and uses a statutory percentage based on the number of children.
That is not always the end of the analysis.
Parents may also share childcare, unreimbursed healthcare and educational expenses. The agreement may address health insurance, extracurricular activities, tutoring, summer programs, transportation and college costs. Which expenses are mandatory, which require advance agreement and how reimbursement will occur should be stated clearly.
Income can also require closer examination. A parent may receive bonuses, commissions, investment income, business income, employer benefits or other compensation beyond a base salary. Tax returns provide essential information, but they do not always reveal the full economic picture.
Parenting arrangements may affect how support is analyzed, but equal or nearly equal parenting time does not automatically eliminate child support.
Child support belongs to the child. Parents have some room to negotiate, but an agreement that departs from the statutory calculation must contain the required information and acknowledgments.
Taxes Can Change the Value of a Settlement
A divorce settlement should not treat taxes as an afterthought.
Transfers of property between spouses incident to divorce may receive particular federal tax treatment, but a later sale can still create taxable gain. Retirement withdrawals may generate income tax and, depending on the circumstances, penalties. Investment accounts may contain unrealized gains. The tax treatment of spousal maintenance depends in part on when the governing agreement was executed and which law applies.
The parents should also address dependency-related tax benefits. Who may claim a child, under what conditions and in which years? Will the required tax forms be signed? What happens if the designated parent is not eligible to use the benefit?
The sale of the marital home can raise questions about capital-gain exclusions, ownership and occupancy. A business transfer may create additional consequences.
Divorce attorneys identify the legal issues, but complex settlements may also require advice from an accountant or tax professional. The agreement should reflect that analysis before it becomes binding.
Health Insurance, Life Insurance and Other Coverage
Health coverage frequently changes after divorce. A spouse who was insured through the other spouse’s employer generally cannot remain covered as a spouse indefinitely after the marriage ends.
Available alternatives may include continuation coverage, an employer plan, a marketplace policy or another private arrangement. The cost and timing of replacement coverage should be investigated before the divorce becomes final.
Children’s coverage should also be addressed. The agreement may specify which parent maintains health insurance and how premiums and uncovered expenses will be allocated.
Life insurance may secure child support, maintenance or other obligations. If insurance is required, the agreement should identify the amount, duration, beneficiary, ownership and proof-of-coverage requirements.
Property, automobile, disability and long-term-care insurance may need review as well. Coverage should match the ownership and obligations established by the settlement.
Attorney Fees and Expert Costs
New York courts may direct one spouse to contribute toward the other spouse’s attorney fees and litigation expenses. The law seeks to reduce unfairness when one spouse has substantially greater financial resources.
A fee award is not automatic. Courts examine the parties’ finances, the circumstances of the case and their conduct, among other considerations.
Experts create additional expenses. A case involving a business, pension, real estate, separate-property claim or disputed income may require an appraiser, forensic accountant or other financial professional.
Those costs should be weighed against what is at stake. Spending heavily to litigate an issue of limited value may make little economic sense. Failing to investigate a major asset can be far more expensive.
Sound strategy requires both legal judgment and proportionality.
Temporary Financial Obligations During the Divorce
The final settlement is not the only financial concern. Bills continue while the divorce is pending.
One spouse may seek temporary maintenance, child support, payment of household expenses or attorney fees. The court may also address temporary possession of the marital home and other immediate issues.
New York’s automatic orders generally restrict both spouses from making certain changes to property, insurance and retirement assets after a matrimonial action begins. These orders are designed to preserve the financial status quo while the case proceeds.
Do not sell, transfer, conceal or borrow against significant assets without first obtaining legal advice. The same warning applies to changing beneficiaries, cancelling insurance or making unusual withdrawals.
An impulsive financial decision made at the beginning of a case can shape negotiations, and the court’s view of your conduct, later.
Preparing a Realistic Post-Divorce Budget
A proposed settlement cannot be evaluated solely through asset values and support calculations. You need to know whether it will fund your actual life.
Prepare a budget based on the household you expect to maintain after divorce. Housing, utilities, food, transportation, healthcare, insurance and children’s expenses should be included. So should irregular costs such as home repairs, vehicle replacement, professional fees and travel between households.
Be candid. An artificially low budget may cause you to accept inadequate support. An inflated budget can undermine credibility and prevent realistic negotiations.
Cash flow and net worth are different. A spouse may receive valuable but illiquid property while lacking money for monthly expenses. Another may have strong income but little retirement security.
The settlement should balance present needs against long-term stability.
Practical Examples
Keeping the House but Losing Financial Flexibility
A spouse wants to remain in the marital home in Suffolk County so the children can stay in the same school district. In exchange for the other spouse’s equity, that spouse gives up a claim to retirement assets.
The arrangement preserves stability today, but it also concentrates wealth in an expensive, illiquid asset. Before agreeing, the spouse should examine refinancing, maintenance costs, future repairs and the effect of surrendering retirement savings.
An Equal Account Division That Is Not Economically Equal
A Nassau County couple has two investment accounts that are each worth $300,000. One contains cash and securities with little unrealized gain. The other contains highly appreciated stock.
Dividing one account to each spouse appears equal. After taxes, it may not be.
A Business Owner’s Reported Salary Does Not Tell the Whole Story
One spouse reports a modest salary from a closely held business on Long Island. The company also pays certain personal expenses and retains substantial earnings.
Determining income for support may require reviewing the business records rather than relying only on the salary shown on a W-2.
Joint Debt Survives the Divorce Agreement
A settlement states that one spouse will pay a jointly held credit card. The account remains open in both names. Payments later stop, and the creditor contacts the other spouse.
The agreement may provide a claim against the spouse who failed to pay, but it did not remove the creditor’s contractual rights. Paying and closing the account during the divorce might have avoided the problem.
Common Financial Mistakes in Long Island, New York Divorce
Negotiating Before Financial Disclosure Is Complete
You cannot make an informed agreement without knowing what exists. Obtain the relevant records before valuing or waiving claims.
Assuming Everything Will Be Split 50/50
Equitable distribution means fair under the circumstances, not automatically equal. Classification, valuation and statutory factors matter.
Looking Only at Present Value
Taxes, liquidity, income potential and future expenses can make assets with similar stated values very different.
Keeping the House Without Testing Affordability
Emotional attachment and stability matter, but the mortgage, taxes, insurance and maintenance must fit the post-divorce budget.
Forgetting Retirement Implementation
A settlement provision does not always divide a retirement plan by itself. The required order or plan documentation must be completed.
Ignoring Joint Credit
A promise between spouses may not bind a lender or credit-card company. Joint accounts should be addressed directly whenever possible.
Using Child Support to Negotiate Property
Child support and property division serve different purposes. Combining them carelessly can create legal, financial and enforcement problems.
Signing First and Asking Tax Questions Later
Tax advice received after the agreement is executed may identify a problem that can no longer be fixed.
## Speak With a Long Island Divorce Attorney About Your Financial Future
Your financial rights in divorce cannot be reduced to a standard percentage or a short list of entitlements. Property classification, income, debt, taxes, support, insurance and future expenses interact. A decision that improves one part of the settlement may create a problem somewhere else.
The attorneys at The Long Island Divorce & Family Law Group, Hornberger Verbitsky, P.C., help clients throughout Nassau County and Suffolk County identify marital assets, evaluate financial obligations and negotiate settlements designed to support life after divorce. When an agreement cannot be reached, we are prepared to protect our clients through litigation.
Call 631-923-1910 for a Complimentary Matter Review.
About Robert E. Hornberger, Esq.
Robert E. Hornberger, Esq., is the founding attorney and managing partner of The Long Island Divorce & Family Law Group, Hornberger Verbitsky, P.C. For more than 20 years, he has represented Long Island clients in contested and uncontested divorce, equitable distribution, spousal maintenance, child support, business valuation and other matrimonial matters.
Mr. Hornberger is licensed to practice law in New York and earned his law degree from the Maurice A. Deane School of Law at Hofstra University. His approach to divorce begins with a practical understanding of the client’s finances: what exists, what must be protected, what obligations may continue and what settlement will provide a workable foundation for the next stage of life.
“Beyond happy with the amazing job Robert did with my family court custody matter. He handled everything professionally and with great ease. Went in uneasy about what was going to happen and Robert made me feel so much better and got me everything I wanted and more. I recommend him to everyone and anyone who is looking for a family court and divorce attorney.”
SCHEDULE YOUR FREE CONSULTATION TODAY
Call 631-923-1910 or fill in the form below
Schedule your complimentary consultation and case evaluation with our experienced attorneys today. When you call, you’ll speak to our friendly Client Services Director, who will be able to answer your general questions and set up your appointment with an attorney who specializes in your unique case.
At your meeting, your attorney will describe the many options available and determine together which is the right solution for you. By the end of this meeting we’ll all understand how we can best help you to move forward.
No Cost or Obligation
There is no cost or obligation for this initial consultation. It is simply an opportunity for us to get to know each other, answer your questions and learn if The Long Island Divorce & Family Law Group, Hornberger Verbitsky, P.C. is right the right law firm for you.
Frequently Asked Questions About Financial Rights in New York Divorce
Is a spouse automatically entitled to half of everything?
No. New York uses equitable distribution. Marital property is divided fairly after considering the applicable circumstances. Some assets may be divided equally, but a 50/50 result is not automatic.
Does property in my name belong only to me?
Not necessarily. Property acquired during the marriage may be marital even if only one spouse’s name appears on the title or account. The source and timing of the acquisition usually matter more than title alone.
Can I keep property I owned before marriage?
Premarital property may be separate, but you must be able to identify and trace it. Mixing the property with marital funds, retitling it or using marital resources to increase its value can complicate the claim.
Is an inheritance divided in divorce?
An inheritance received by one spouse is generally considered separate property. That protection can become more difficult to establish if the inherited funds were placed into joint ownership, mixed with marital money or used in a way that created a marital claim.
Who gets the marital home?
There is no automatic rule. The home may be sold, transferred to one spouse or retained jointly for a limited period. Affordability, equity, custody arrangements and the overall property settlement may affect the result.
Are retirement accounts divided even if only one spouse worked?
The portion earned or contributed during the marriage may be marital property regardless of whose employment produced the benefit. Premarital contributions may remain separate if they can be established.
Am I responsible for debt in my spouse’s name?
Possibly. Debt incurred during the marriage for marital or household purposes may be considered in the divorce even if only one spouse’s name appears on the account. The facts surrounding the debt matter.
Will I receive or pay spousal maintenance?
Maintenance is not automatic. New York uses statutory calculations and factors that consider income, the length of the marriage and other circumstances. The amount and duration depend on the facts of the case.
Does equal parenting time eliminate child support?
Not automatically. New York’s child-support analysis considers parental income and applicable custody circumstances. Shared parenting time does not, by itself, guarantee that neither parent will pay support.
Who pays the children’s expenses beyond basic child support?
Parents may also be responsible for childcare, healthcare, education and other agreed expenses. The settlement or court order should explain which costs will be shared and in what proportions.
Can my spouse change beneficiaries or move money after divorce papers are filed?
New York’s automatic orders restrict certain transfers, withdrawals and insurance changes while a matrimonial action is pending. Speak with an attorney before taking or responding to any unusual financial action.
Who pays the attorneys and financial experts?
Each spouse may initially pay his or her own expenses, but a court can direct one spouse to contribute toward the other’s attorney or expert fees. Financial disparity and litigation conduct may affect that decision.
Can my spouse and I create our own financial agreement?
Yes. Spouses can negotiate terms rather than asking a judge to decide every issue. The agreement must be complete, properly prepared and executed, and child-support deviations require specific statutory language.
Can the financial settlement be changed after divorce?
Property-division terms are generally intended to be final. Maintenance or child-support provisions may sometimes be modified when legal requirements are satisfied. Do not sign an agreement on the assumption that it can easily be changed later.


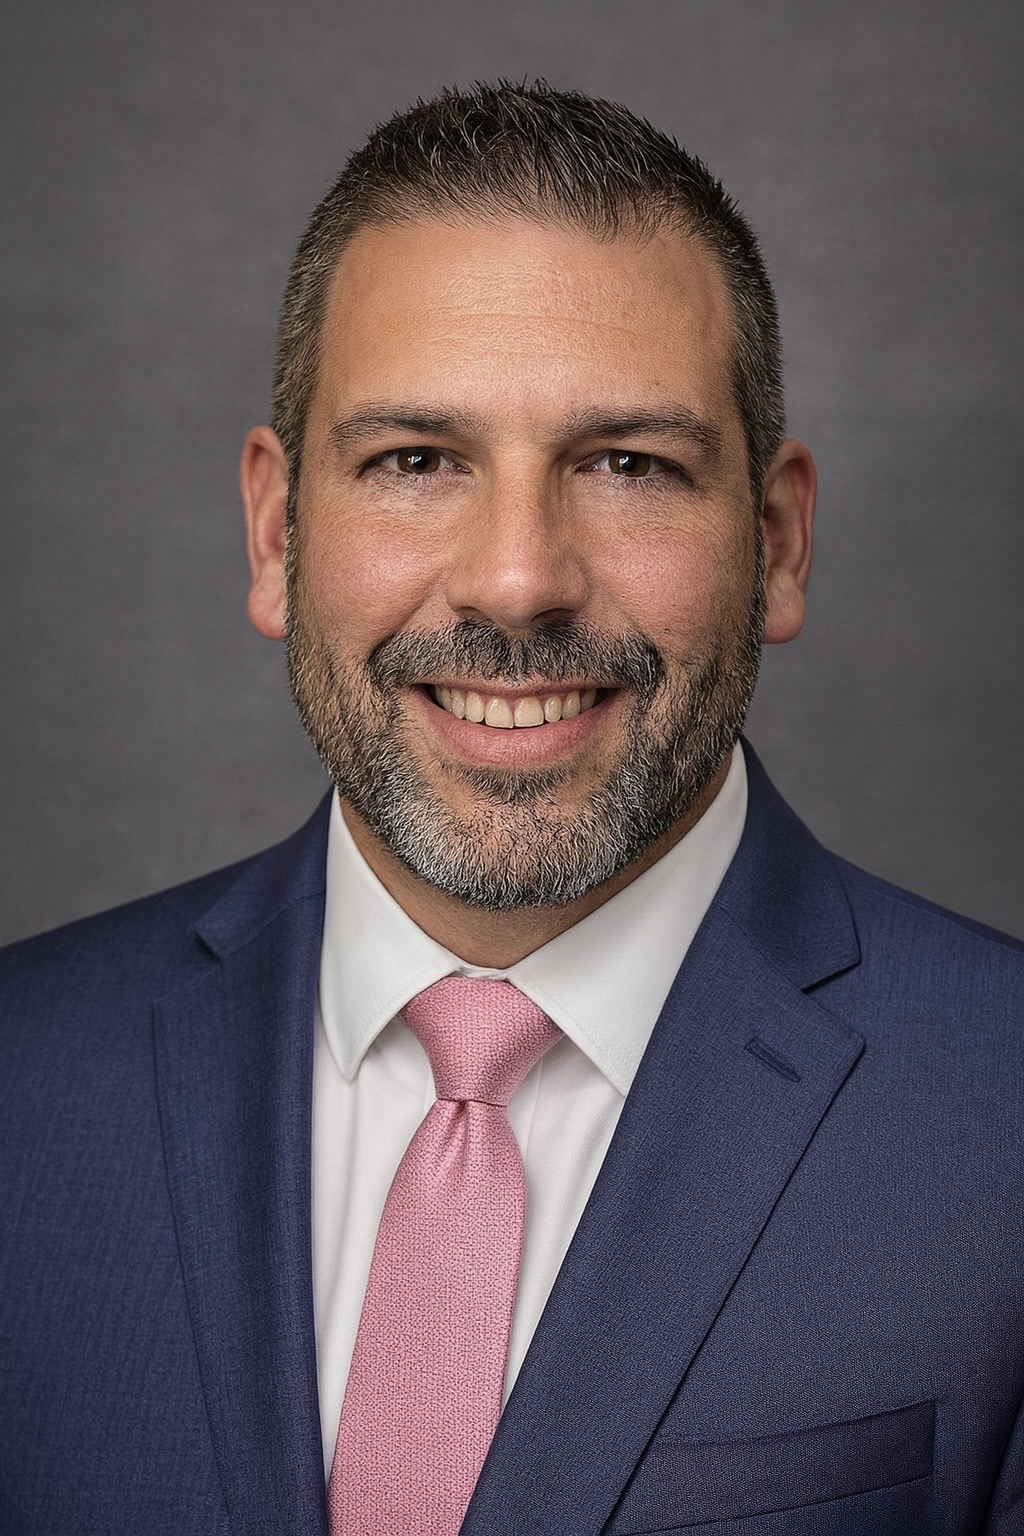
About the Author
Robert E. Hornberger, Esq., Founding Partner, The Long Island Divorce & Family Law Group, Hornberger Verbitsky, P.C.
Robert E. Hornberger, Esq. is the founder and managing partner of The Long Island Divorce & Family Law Group, Hornberger Verbitsky, P.C., a Long Island family law firm representing clients throughout Nassau County and Suffolk County. Since 2006, he has represented individuals in matters involving divorce, equitable distribution, child custody, child support, spousal maintenance, divorce mediation, high-net-worth divorce, business valuation, prenuptial agreements, and other complex family law issues. Robert is recognized by numerous professional organizations for his work in family law and regularly provides guidance to clients navigating sophisticated financial issues under New York law.
- Over 20 years practicing matrimonial law
- Over 1,000 cases successfully resolved
- Founder and Partner of The Long Island Divorce & Family Law Group, Hornberger Verbitsky, P.C.
- Experienced and compassionate Long Island Divorce Attorney, Family Law Attorney, and Divorce Mediator
- Licensed to practice law in the State of New York
- New York State Bar Association member
- Nassau County Bar Association member
- Suffolk County Bar Association member
- “Super Lawyer” Metro Rising Star
- Nominated Best of Long Island Divorce Attorney four consecutive years
- Alternative Dispute Resolution Committee Contributor
- Collaborative Law Association of New York – Former Director
- Martindale Hubbell Distinguished Designation
- America’s Most Honored Professionals – Top 5%
- Lead Counsel Rated – Divorce Law
- American Institute of Family Law Attorneys 10 Best
- International Academy of Collaborative Professionals
- Graduate of Hofstra University School of Law
- Double Bachelor’s degrees in Philosophy, Politics & Law and History from SUNY Binghamton University
- Full Robert E. Hornberger, Esq. Bio